Advertiser DISCLOSURE


The Chase 5/24 Rule Explained
If you plan to open 2 credit cards per year, and have your partner open 2 credit cards per year – you will NEVER have to worry about this rule I’m about to explain. BUT if you’re a little extra (like us) OR if you want to be traveling extra (like us) – listen up.
If you’re a fan of rewards credit cards, you’ve probably heard the mention of the infamous “Chase 5/24 Rule.” This rule is HUGE if you’re looking to open multiple credit cards. Especially those cards offered by Chase Bank, which include some of the best travel cards on the market. Here, we’ll explain what the 5/24 Rule is, how it works, and strategies for maximizing your approval chances. Because we all know its the absolute worst getting denied for a credit card.
First, I want to address an important update:
⚠️ September 2026 Update⚠️
Update (September 2026): Data points suggest Chase may have implemented a 3/24 rule for sole proprietors applying for business cards. Particularly Ink cards. If you apply for Chase business cards as a sole proprietor using your SSN, you may be denied if you’ve opened 3 or more cards in the past 24 months, regardless of your 5/24 status. Registered businesses (LLCs, corporations) appear to still operate under the standard 5/24 rule. This is an unofficial policy based on applicant data points, not a confirmed Chase announcement. But it’s significant enough to factor into your strategy. More on this below. But for now, let’s go back to learning about 5/24.
What is the Chase 5/24 Rule?
The Chase 5/24 Rule is an officially unofficial policy Chase uses when reviewing applications for most of its credit cards. It’s simple but strict: if you’ve opened five or more personal credit cards (from any issuer) in the past 24 months, Chase will likely deny your application for a new card. It applies regardless of your credit score, income level, or overall creditworthiness (is that a thing??), so even well-qualified applicants can be affected.
For instance, if you’ve opened five new credit cards in the last two years, applying for a popular Chase card, like the Chase Sapphire Preferred® Card (this is the first card I ALWAYS recommend to beginners!) or the Chase Freedom Unlimited®, will likely result in a rejection.
Exceptions: A few Chase cards may be exempt from this rule, but these exceptions are rare.
How Does the 5/24 Rule Work? And Possibly the 3/24 Rule?
The 5/24 Rule counts all personal credit cards opened in the last 24 months, even those from other banks. Here’s how it breaks down:
- Credit Cards Counted: The rule includes personal credit cards from Chase and other issuers, such as American Express, Citibank, Bank of America, and Capital One. Even store credit cards from retailers like Old Navy, Home Depot, and Amazon can count (you know how I feel about these store credit cards – don’t open them). In my opinion, they are rarely worth filling up a 5/24 slot).
- Business Cards Impact: Generally, business cards don’t count toward the 5/24 limit, as they don’t typically appear on your personal credit report. If you’re a sole proprietor applying for Chase business cards with your SSN (rather than an EIN for a registered business), recent data points suggest Chase may be applying a stricter 3/24 threshold to your application. If you’re serious about the Chase ecosystem (especially the Southwest Companion Pass) this makes your card sequencing and business structure fairly important!
- Authorized User Accounts: Accounts where you’re an authorized user may count toward your 5/24 tally. However, if these push you over the limit, you can often call Chase to explain. They may disregard these accounts, or even remove them. In general, I recommend not adding your spouse/partner as an authorized user. If you want to share a credit card, I’d recommend adding the card to your partners digital wallet.
Strategies for Navigating the 5/24 Rule
If you’re interested in Chase’s credit cards but are close to or have exceeded the 5/24 limit, here are some strategies to work within the rule:
- Space Out Card Applications: Avoid opening too many cards in a short period. I recommend spacing applications 90 days apart. Here’s the rule of thumb we follow in my home: Amber Personal Card ➡️ Devin Personal Card ➡️ Amber Business Card ➡️ Devin Business Card ➡️ repeat process.
- Stagger between Player 1 and Player 2: If you and a spouse or partner are both building Chase points, coordinating who applies and when becomes even more critical under a potential 3/24 environment. Spacing applications between two players can effectively double your earning without either person hitting a wall.
- Consider Business Cards: Business cards from most issuers (such as American Express, Citibank, or even Chase itself) typically don’t show up on your personal credit report. Which means they usually won’t count toward your 5/24 limit. If you have a small business or a side hustle such as tutoring, owning an investment property, photography, or selling things on Facebook Marketplace, consider a business card to continue earning rewards without impacting your 5/24 status. Read my blog article here for more info on How to Open a Business Card without a Traditional Business.
- Know your business structure: Sole proprietors applying with an SSN appear to face a tighter 3/24 window for Chase business cards, while registered LLCs and corporations still appear to qualify under the standard 5/24 rule. If you’re deep in the Chase strategy, forming an LLC may be worth exploring with a tax professional.
- Remove Authorized User Accounts (If Necessary): Really, I’d just slap your hands and say “don’t do it again.” But if you feel like you MUST remove yourself as an authorized user, contact the bank and ask if you can be removed as an authorized user.
- Target Cards Outside Chase After Reaching 5/24: If you’ve hit the 5/24 limit, focus on business cards from issuers that don’t follow such strict rules, like American Express or Citibank. This approach lets you continue building rewards while you wait for your status to reset with Chase.
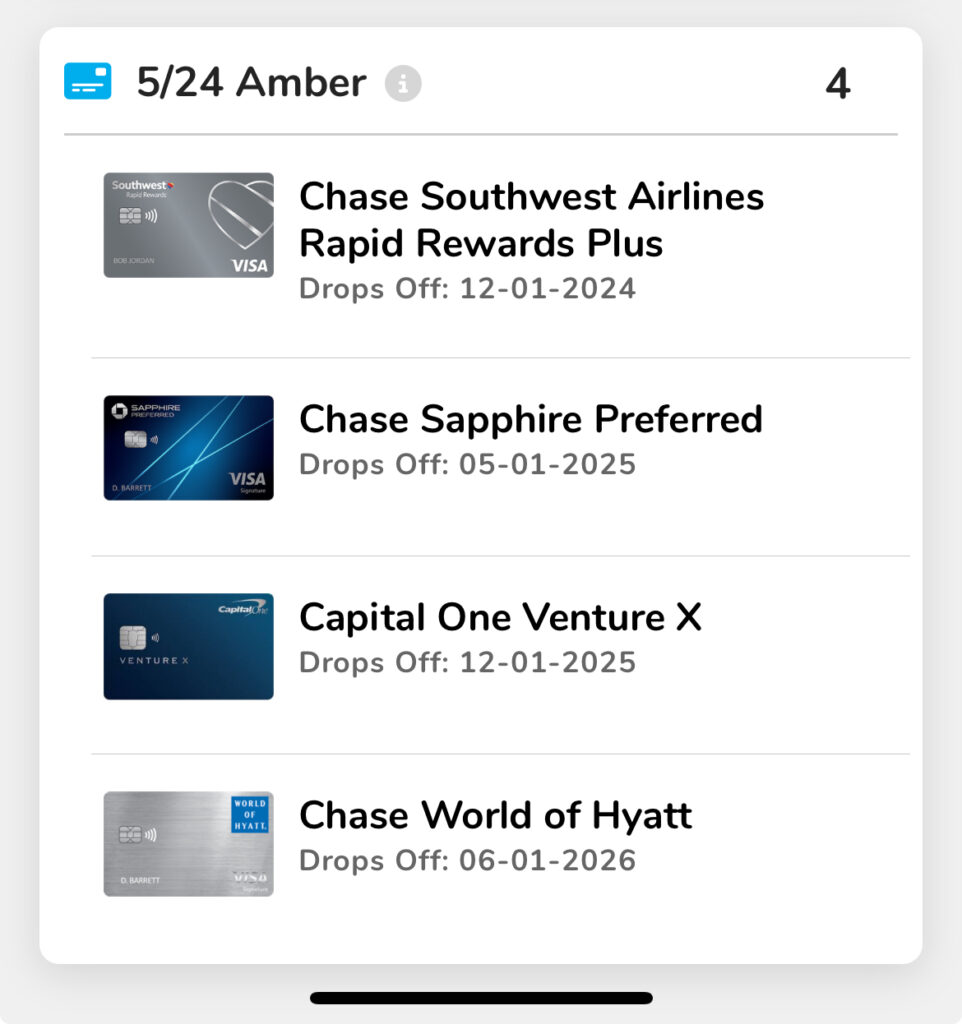
- Track Your Applications: Using a spreadsheet or an app to track your applications keeps you aware of your 5/24 limit. I LIVE BY my Travel Freely App (affiliate link but it costs you nothing!). This requires NO sensitive information and even sends me an email when one of my annual fees are approaching!
Conclusion
The rules are always evolving. As of late 2026, sole proprietors in particular may benefit from checking current data points before applying for Chase business cards as an unofficial 3/24 rule appears to be in effect.
That said, by understanding the 5/24 Rule and how it impacts your credit card application strategy, you’ll be set up for long term travel rewards success. This is the only way we have been able to do this since 2013. In my opinion, slow and steady (but probably faster than you’re doing it now…? wins the race). We want to protect our credit score while earning huge chunks of travel rewards. Whether you’re a points enthusiast or just starting, minding this rule will help you travel smarter and maximize your rewards. Let’s get you traveling (on points)!


Terms apply to American Express benefits and offers. Enrollment may be required for select American Express benefits and offers. Visit americanexpress.com to learn more. For Capital One products listed on this page, some of the above benefits are provided by Visa® or MasterCard® and may vary by product. See the respective Guide to Benefits for details, as terms and exclusions apply.
EDITORIAL NOTE:
Opinions expressed here are the author’s alone, not those of any bank, credit card issuer, hotel, airline or other entity. This content has not been reviewed, approved or otherwise endorsed by any of the entities included with the post.
Amberonpoints is part of an affiliate sales network and may earn compensation when a customer clicks on a link, when an application is approved, or when an account is opened. This relationship may impact how and where links appear on this site. This site does not include all financial companies or all available financial offers. We appreciate it when you use our affiliate links as it supports our content at no cost to you!
Terms apply to American Express benefits and offers. Enrollment may be required for select American Express benefits and offers. Visit americanexpress.com to learn more. For Capital One products listed on this page, some of the above benefits are provided by Visa® or MasterCard® and may vary by product. See the respective Guide to Benefits for details, as terms and exclusions apply.
EDITORIAL NOTE:
Opinions expressed here are the author’s alone, not those of any bank, credit card issuer, hotel, airline or other entity. This content has not been reviewed, approved or otherwise endorsed by any of the entities included with the post.